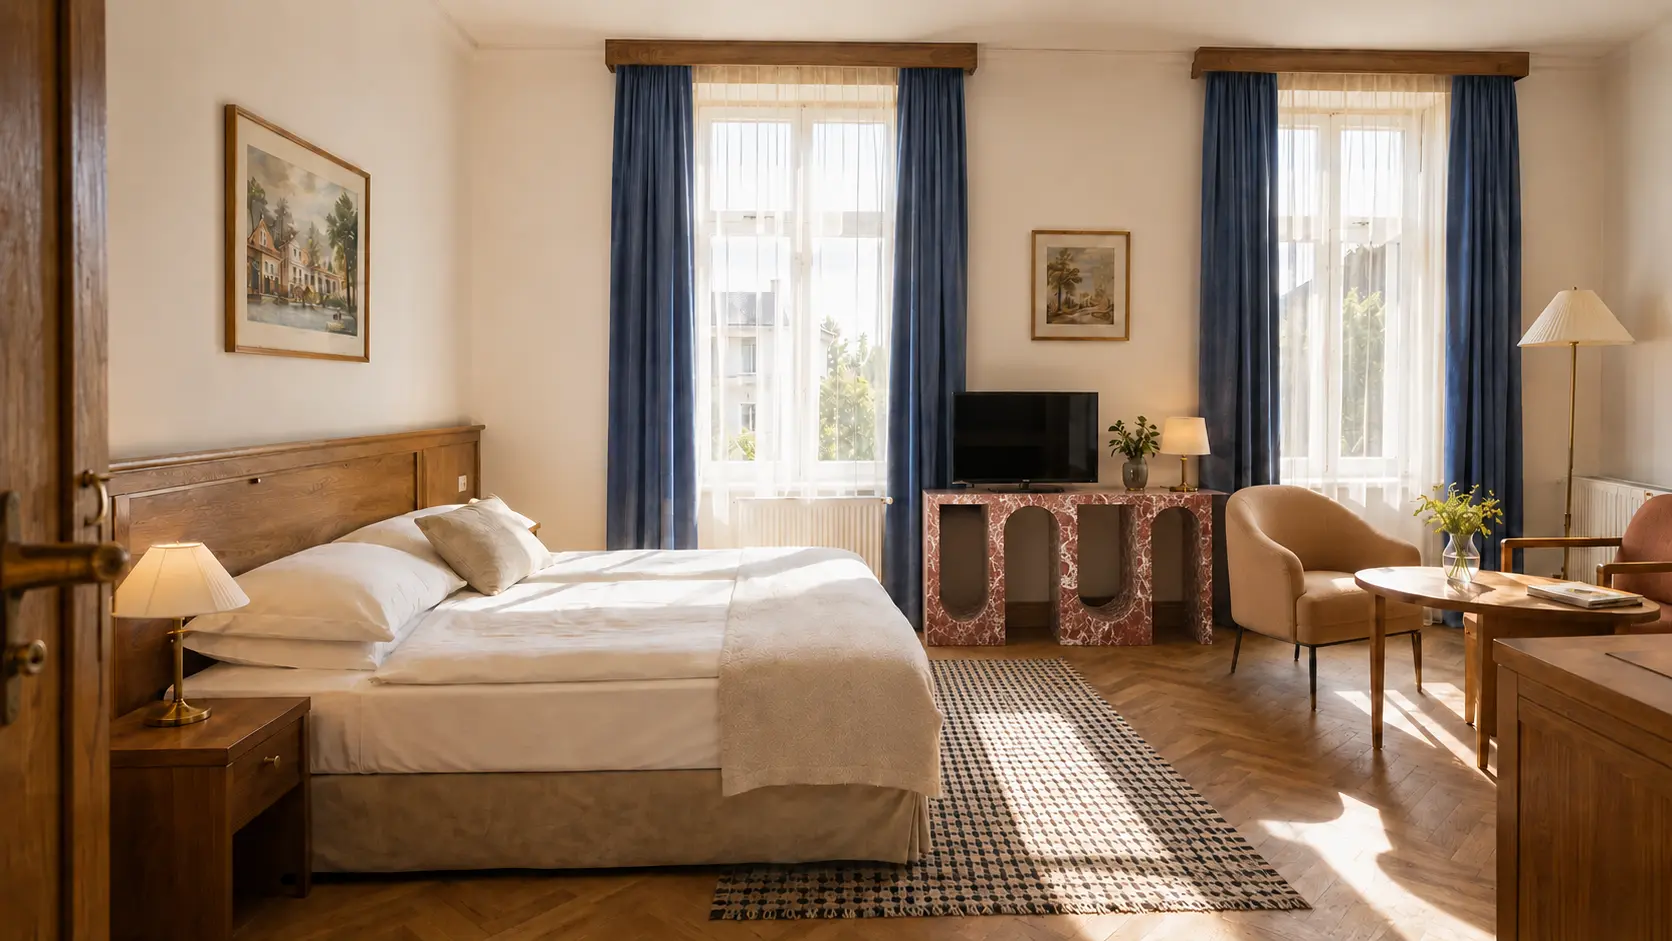
The first three routes are the strongest marketing narratives. The remaining options should be presented selectively and only after feasibility checks.
A design-led repositioning built around the protected architecture, generous rooms and a premium spa-weekend proposition.
Relative capex
High
Execution complexity
Medium–high
Indicative launch
12–20 months
Buyer profile
Value-add hospitality investor, design-hotel operator or private investor with renovation expertise.
Income model
Ten differentiated keys, premium ADR, direct sales, breakfast and a compact wellness offer.
Critical condition
A rate premium depends on disciplined design, heritage approvals and a verified refurbishment budget.
Interactive underwriting
Make the assumptions yours.
Adjust the acquisition, capex and operating assumptions. The chart recalculates the annual NOI and capital recovery for this scenario in real time.
Model assumptionsIllustrative scenario preset · Boutique hotel
10 guest rooms · existing configuration
10 × €130 × 65% × 365
Annual room revenue
€308,425
Total stabilized annual revenue
€358,425
Total project capital€1,980,000Stabilised annual NOI€100,359Yield on total cost5.1%Modelled unlevered IRR4.7%Capital recovered from operations54%Net position after modelled sale€929,438
Illustrative inputs, not current trading data. Room revenue uses 10 rooms; extra beds add no automatic revenue. Other revenue is entered separately; avoid counting packaged services twice. Medical and alternative-use scenarios require feasibility review.
Illustrative, user-controlled model only. Presets are hypotheses, not current performance or forecasts. It excludes debt, tax, transaction costs, working capital, inflation and unplanned capex. Exit value equals the following year’s NOI divided by the selected exit yield.
Decision matrix
Six routes, one disciplined framework.
Use case
Strategic fit
Capex
Launch
Complexity
Key risk
Priority 1
High
12–20 months
Medium–high
Heritage approvals and renovation cost
Priority 2
Medium–high
15–24 months
High
Partner demand and accessibility
Priority 3
Medium
9–15 months
Medium
Strategic-buyer dependency
Supporting
Low–medium
4–8 months
Low–medium
Small scale and owner dependence
Conditional
High
18–30 months
High
Change-of-use and subdivision consent
Specialist only
Very high
24–36+ months
Very high
Licensing and technical suitability
Scenario assessment is strategic and illustrative. It is not a business plan, forecast, permission opinion or guarantee of returns.
Verified property snapshot
The asset, at a glance.
10guest rooms808 m²total building area745 m²land parcel KN-C 47on-site parking spacesF&Brestaurant and kitchenWellnesssauna and whirlpoolLiftserving all floorsHeritageprotected historic building
Source: seller-provided property data, the 2024 full appraisal and June 2026 appraisal summary.
Documents & owner confirmation
Layout & spaces
The hotel, floor by floor.
Ten guest rooms, restaurant spaces and an operational wellness area. Explore the existing layout, confirmed by the owner.
Guest rooms
Shared spaces
Wellness
Building services
Balconies
Ground floor
Reception, dining & hospitality
The reception, restaurant and separate salon are supported by a kitchen, sanitary facilities and service spaces.
01Separate salon
42 m²
02Kitchen
35 m²
03Restaurant
65 m²
04Reception
25 m²
CCirculation
OOffice
EEntrance vestibule
SService & sanitary spaces
Presentation plans redrawn from the owner’s drawings, preserving the layout and proportions, without dimensions or technical annotations. Areas from the owner include bathrooms. Basement hatching marks unexcavated areas. Roof windows are shown on the roof level; dashed lines indicate roof slopes.
Lift, kitchen, sauna and whirlpool operational, as confirmed by the owner.
20 main beds + 5 additional beds. Extra beds are suitable for adults and children, according to the owner.
Separate attic · approx. 115 m²
Excluded from the stated 808 m² building area. No separate attic plan was supplied; any future use requires a feasibility review.
The stated transaction is an asset deal at a negotiable asking price of €1.58m. Title, seller authority and tax treatment remain subject to due diligence.
01
Real estate
Building no. 564 and parcel KN-C 4 with 745 m² of land. Current land-registry evidence will be provided in the data room.
02
Operating platform
The stated sale perimeter is the real estate. Any transfer of operating assets, contracts or the company would require a separate agreement.
03
Confirmed terms
Asset dealBuilding + land€1.58m · negotiable
The seller states that the secondary-market sale is VAT-exempt. This treatment should be confirmed by the parties' tax advisers.
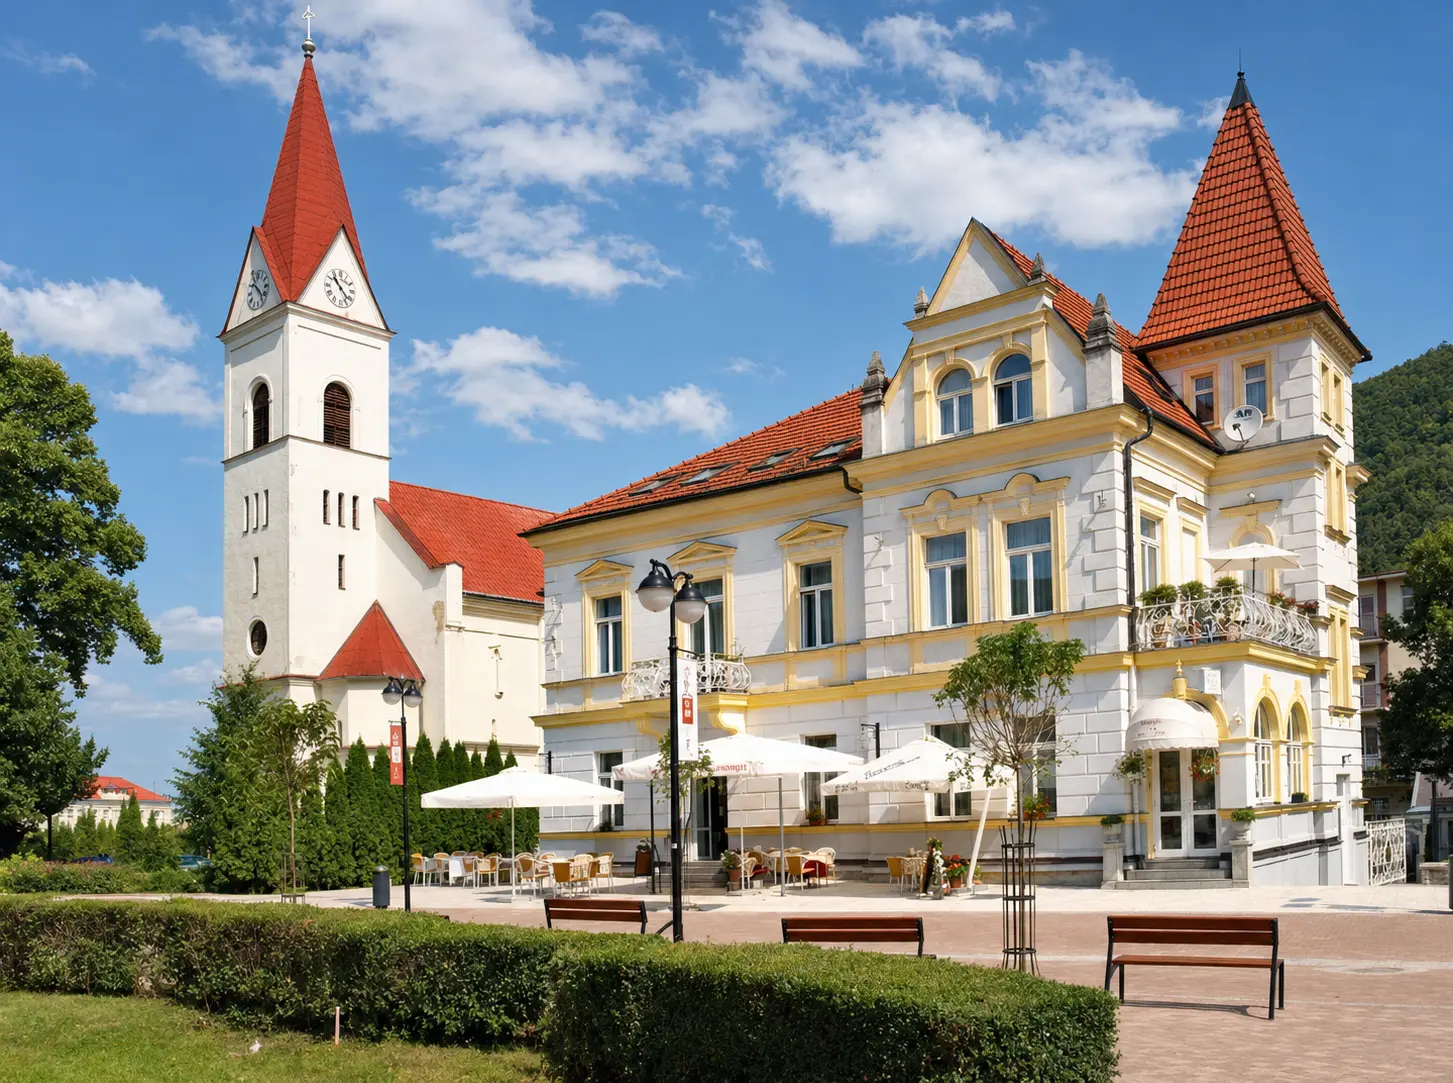
Digitally refined from an authentic property photograph · T. G. Masaryka 2
Expert appraisal · June 2026
€1.46m
Rounded appraised real-estate value
Valuation date · June 2026Asking price · €1.58m · negotiable
The appraisal provides an asset-value anchor for the building, land and site improvements. It does not demonstrate current operating yield and should be tested against legal, technical and commercial due diligence.
Appraised value composition
Main building€1.167m
Land€270.9k
Other site improvements€27.2k
No registered encumbrances were identified in the June 2026 appraisal. Current land-registry documentation is available during due diligence.
Documents & owner confirmation
Income test
What NOI must the €1.58m asking price support?
This is the annual net operating income required to support selected unlevered property yields at the asking price, before additional acquisition costs and capex.
Target yieldRequired annual NOI
5%
€79,000
6%
€94,800
7%
€110,600
8%
€126,400
9%
€142,200
Threshold analysis only. These figures are neither current results nor forecasts; financing, tax, transaction costs and renovation capex are excluded.
Illustrative assumption
Technical chronology
Historic prestige, understood constraints.
The building has been repeatedly upgraded and was described in the 2024 appraisal as being in good technical condition with routine maintenance. A buyer should still commission an independent building survey and capex plan.
01c. 1914Original use
Historic hospitality building
021991–1999Major works
Extensive reconstruction period
032004Wellness
Sauna and whirlpool added
042017Plant
Boiler equipment renewed
0558.93%Technical condition
2024 appraiser’s calculated condition
06ProtectedStatus
Cultural-monument controls apply
↳
Heritage is both the story and the constraint.
It strengthens identity and scarcity, but may affect design approvals, capex and timing. The appraisal assumes no significant physical expansion of the building.
Controlled due diligence
What a serious buyer still needs.
01
Current title extract, seller authority and exact transaction perimeter
02
Measured plans, attic area confirmation and parking documentation
03
Three years of monthly occupancy, ADR, RevPAR and channel mix
04
Full P&L, normalised EBITDA/NOI bridge and working-capital position
05
Independent building survey, façade scope and five-year capex plan
06
Planning, heritage, fire, accessibility and alternative-use opinions
Private investment opportunity · Slovakia
The investment case.
A protected 10-room hospitality property with an operating platform, an expert real-estate appraisal and several credible repositioning routes in an established spa destination.
Decision basis
The June 2026 appraisal indicates €1.46m. The negotiable asking price is €1.58m for an asset sale comprising the building and land.
Documents & owner confirmationIllustrative assumptionTo be confirmed
Confidential next step
Move from presentation to evidence.
Qualified parties can request the investment memorandum, supporting data room or a confidential introductory call.